Retirement planning for single women involves more than deciding how much money to save. Whether you’re single by choice, divorced, or widowed, you want to know that your financial resources can support you throughout retirement. But financial security is only part of the equation. What do you want your retirement to look like?
Financial security matters. You want to feel confident your money will last, even if the markets decline, unexpected expenses arise, or you live longer than anticipated. At the same time, retirement gives you a chance to think about what matters most to you and how you want to spend your time.
At Apprise Wealth Management, we believe the best retirement plans address both concerns. The process begins with understanding the life you want to live and using that information to guide your financial decisions.
You can’t predict everything retirement will bring. But you can prepare for uncertainty, understand your options, and adjust as circumstances change.
Key Points
|
1. Retirement Planning for Single Women Starts With a Life Plan
When someone approaches retirement, one of the first questions she often asks is, “Do I have enough money?”
It’s an important question. But I believe we should start with another.
Enough money for what?
Before determining whether you have enough money to retire, it helps to understand what you’re retiring to, not just what you’re retiring from.
For many of us, work represents a significant part of our identity. It provides income, but it may also provide purpose, relationships, structure, and a sense of accomplishment.
When we retire, some of those elements change or disappear. That creates an opportunity to explore what comes next.
What would make retirement meaningful to you?
Perhaps you want to travel more, pursue a hobby you’ve always enjoyed, volunteer, spend more time with people you care about, or move somewhere you’ve always wanted to live.
Maybe you want to continue working part-time because you enjoy your work. Or perhaps you’re looking forward to a quieter life with fewer commitments.
There’s no single right answer.
Align Your TEAM of Capital With Your Values
At Apprise, we often talk about your TEAM of Capital: Time, Energy, Attention, and Money.
Money is only one resource you have to build a meaningful life. How you use your time, direct your energy, and focus your attention matters, too. When you align your TEAM of Capital with your values, you can make more intentional decisions about what deserves your resources and what doesn’t.
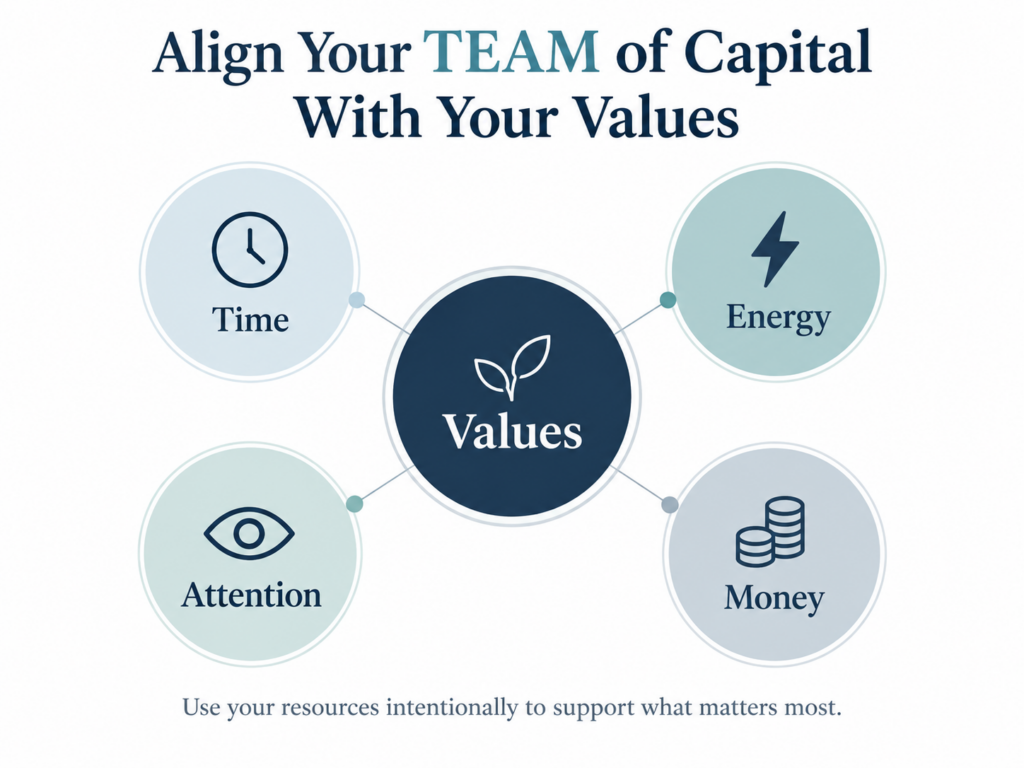
You may discover some things you’ve been spending money on aren’t particularly important to you. At the same time, you might realize that an experience you’ve been postponing deserves a higher priority.
The goal isn’t necessarily to spend less. It’s to spend on what matters most. This is one reason I believe retirement is an especially good time for life planning. It’s a major transition, and transitions often give us a chance to reconsider our priorities.
At Apprise, we generally begin new relationships by exploring what matters most to our clients. That work helps us identify their most important goals and build a financial plan around them. Sometimes an urgent financial issue requires us to address the numbers first. But whenever possible, I believe the life plan should guide the financial plan.
2. Understand Your Financial Starting Point
Once you have a clearer picture of the life you want to live, you can start determining what it will take to support that life financially.
Retirement planning for single women should include a careful review of your assets, liabilities, income sources, and anticipated expenses.
Start by reviewing your net worth, including your savings, investments, other assets, and outstanding debts.
Next, review your current income and expenses.
You don’t need to track every dollar, but it can help. What matters is understanding your spending today and how it might change in retirement.
Consider which expenses are essential and which are discretionary.
Separate essential expenses, such as housing, food, and healthcare, from discretionary spending, such as travel, dining out, and hobbies. Understanding what you can adjust becomes especially important when circumstances change.
Identify Your Retirement Income Sources
Your retirement income might come from several places, including Social Security, pensions, taxable investments, traditional IRAs, Roth IRAs, and employer-sponsored retirement plans.
Some women also expect income from part-time work, consulting, rental properties, or other sources.
If you’re still working, review your retirement savings options, including employer matching contributions, IRAs, catch-up contributions, and, when eligible, Health Savings Accounts.
Once you retire, however, the focus changes. Instead of primarily accumulating assets, you need to determine how to turn those assets into a reliable source of retirement income.
3. Build a Flexible Retirement Plan
Financial planning software can help us evaluate whether your resources can support your desired retirement. One approach, called Monte Carlo analysis, tests your plan across numerous simulated market scenarios and estimates how often your projected resources can meet your planned spending needs.
These projections can be extremely helpful. But they come with an important limitation.
Your Financial Plan Is Not a Prediction
Markets will perform differently than projected. Inflation may be higher or lower than expected. Your spending might change. Your health, family circumstances, and personal priorities may also change.
A financial plan’s probability of success matters, particularly when essential expenses are at risk. But we shouldn’t treat any single probability as a pass-or-fail grade. We also need to understand the assumptions behind the projection and what adjustments might be necessary if circumstances change.
A higher projected probability isn’t always a better outcome if achieving it means unnecessarily sacrificing experiences that would make retirement more meaningful. The key question is whether the plan balances financial security with the life you want to live.
Be Willing to Course-Correct
When speaking with clients, we emphasize the ability to make adjustments along the way.
Suppose the markets perform poorly early in retirement. Or you encounter an unexpected expense. Your financial plan might show a lower probability of success than it did the previous year.
That doesn’t automatically mean your retirement is in trouble. It means we need to reassess your options.
Could you temporarily reduce discretionary spending, postpone a major purchase, or adjust your withdrawal strategy? Knowing which expenses are flexible, and by how much, can help you identify realistic adjustments before you need to make them.
Your willingness and ability to make adjustments can make a significant difference. But flexibility has limits. Someone whose resources barely cover essential expenses has fewer options than someone with substantial discretionary spending. The financial plan needs to account for those differences from the beginning.
Financial confidence doesn’t require certainty about everything that might happen. It comes partly from knowing that you have options when circumstances change.
4. Make Thoughtful Social Security Claiming Decisions
Social Security is an important part of retirement planning for single women, and your marital history can affect the decisions available to you.
For married couples, Social Security decisions should consider both spouses because a higher benefit for one can affect the surviving spouse’s income. For a woman relying on her own retirement benefit, the decision may focus more directly on her life expectancy, financial resources, and income needs. Divorced and widowed women may have additional claiming options.
When Should You Claim Social Security?
If you’re eligible for benefits based on your own earnings record, you can generally begin claiming retirement benefits as early as age 62.
However, claiming early permanently reduces your monthly benefit under the usual rules.
According to the Social Security Administration, delaying retirement benefits until age 70 produces the maximum monthly benefit available based on your earnings record. Waiting beyond age 70 provides no additional delayed retirement credits.
Delaying benefits may make sense if you expect to live a long time and have other resources to support your spending. I’ve worked with clients who chose to wait until age 70 for that reason. But it’s not the right choice for everyone.
When circumstances support it, I often recommend delaying benefits until age 70 while keeping the flexibility to claim earlier if health, finances, or other circumstances change.
The key is to make an informed decision rather than claiming simply because you’ve reached a certain age.
Special Considerations for Divorced and Widowed Women
Your options may differ if you’ve been married before.
If you were divorced after a marriage lasting at least 10 years, you may qualify for Social Security benefits based on your former spouse’s earnings record.
Widows may qualify for survivor benefits, which follow different claiming rules. Unlike retirement benefits based on your own earnings record, survivor benefits generally reach their maximum at survivor full retirement age. In some circumstances, a widow can claim survivor benefits first and later switch to her own retirement benefit, or follow another claiming sequence.
The rules can be complicated, and the best strategy may depend on more than the monthly benefit amount.
For more information, see our blogs on when to claim Social Security, Social Security after divorce, and Social Security survivor benefits.
The takeaway is simple: Evaluate Social Security as part of your overall retirement plan, not as an isolated decision.
5. Coordinate Taxes and Retirement Income
At Apprise, we often say that “taxes and investing are joined at the hip.”
You may have accumulated substantial assets in traditional retirement accounts, Roth accounts, and taxable investment accounts.
But money held in each of these accounts can receive very different tax treatment when you withdraw it.
Withdrawals from traditional IRAs and 401(k)s are generally taxable as ordinary income. Qualified Roth withdrawals can be tax-free. Taxable investment accounts involve other considerations, including dividends, interest, and capital gains.
The accounts you draw from, and when you draw from them, can materially affect your retirement tax bill.
Why Tax Planning Matters for Single Women
Single taxpayers generally have narrower federal income tax brackets than married couples filing jointly. For example, according to the IRS’s 2026 federal income tax brackets, the 24% bracket begins above $105,700 of taxable income for single filers, compared with $211,400 for married couples filing jointly.
That can leave less room for Roth conversions or recognizing additional taxable income without pushing you into higher tax brackets.
For a divorced or widowed woman, a change in filing status may also significantly change her tax situation. That’s why it’s important to think beyond this year’s tax return.
One strategy worth evaluating is a Roth conversion. A Roth conversion involves transferring money from a traditional tax-deferred retirement account to a Roth account and taxes the converted amount as income.
A Roth conversion generally increases taxable income in the conversion year. However, depending on your circumstances, it may reduce future required minimum distributions, provide a source of tax-free retirement income, and improve your long-term tax flexibility.
However, Roth conversions aren’t always beneficial. The conversion creates a current tax obligation and may increase Medicare premiums or affect other income-related costs. The potential long-term benefits must justify those near-term costs.
Good tax planning involves evaluating these trade-offs.
Think About Lifetime Taxes, Not Just This Year’s Taxes
The years between retirement and the start of required minimum distributions may create valuable tax-planning opportunities. If your taxable income falls after you stop working, you may have an opportunity to complete Roth conversions or recognize income at more favorable tax rates.
You should also consider asset location, which involves deciding which investments to hold in taxable, tax-deferred, and Roth accounts.
When possible, coordinating these decisions can improve the tax efficiency of your investments and retirement withdrawals.
The goal isn’t to minimize taxes in any one year. It’s to manage your lifetime tax burden so you can retain more of your resources.
I’ve written more about these considerations in How Is Retirement Income Taxed? and Asset Location for Tax Efficiency.
6. Balance Sequence-of-Returns Risk With Longevity Risk
I believe sequence-of-returns risk and longevity risk are two of the most important investment risks retirees face. Managing them requires balancing near-term stability with long-term growth.
Sequence-of-returns risk involves poor investment returns early in retirement, when you begin withdrawing money from your portfolio.
If you must sell investments after they’ve declined significantly, those withdrawals can reduce the assets available to participate in a market recovery.
Longevity risk is the possibility of living longer than your financial resources can support.
These risks create competing demands. You need enough stability to cover near-term withdrawals during difficult markets, but you also need growth potential because retirement could last 25, 30, or more years.
Why Becoming Too Conservative Can Be Risky
Sometimes retirees become so concerned about losing money that they move too much of their portfolios into cash or other conservative investments.
A more conservative portfolio may reduce short-term volatility. However, it can also increase the risk that your investments won’t grow enough to keep pace with inflation and support a long retirement.
The objective isn’t to maximize investment returns or outperform a benchmark. It’s to build a portfolio that supports your financial plan while managing the risks that matter most to you.
How We Approach Cash Reserves at Apprise
One way we manage sequence-of-returns risk is by maintaining a cash or money market cushion.
We size the cash cushion based on the amount a client needs from their investment portfolio, not their total living expenses. After accounting for interest and dividend income available to fund those withdrawals, we generally aim to maintain about 24 months of remaining withdrawal needs in money market funds or short-term Treasuries.
If the stock market experiences a significant downturn, available cash can reduce the need to sell equities at depressed prices, potentially giving those investments more time to recover.
If a downturn continues, the portfolio’s fixed-income allocation may provide another source of funds.
This approach doesn’t eliminate risk. Fixed-income investments can decline in value, and a prolonged market downturn could require us to sell other investments. Maintaining cash also has an opportunity cost because those funds may earn less than long-term growth investments. We must balance that trade-off against the flexibility a cash cushion provides.
We typically replenish the cash cushion by selling appreciated investments or when rebalancing portfolios. We also consider the tax consequences when deciding which investments to sell.
This approach helps us meet near-term withdrawal needs while keeping other assets invested for long-term growth. It also illustrates why investment management, tax planning, and retirement income planning belong together.
7. Remember Your Health Line and the Retirement Spending Smile
One of the challenges of retirement planning is finding the right balance between protecting your financial future and enjoying the present.
After decades of saving and investing, spending from your portfolio can feel uncomfortable. You may worry that spending too much today means you won’t have enough tomorrow. Those concerns deserve attention. But there’s another risk worth considering.
You can become so focused on preserving your money that you postpone experiences you may not always be able to enjoy.
Your Bucket List Needs a Health Line
I’ve written before about the importance of putting a health line alongside your bucket list.
Some experiences get harder as we age. Activities such as extensive travel, hiking, or other physically demanding pursuits may be easier to enjoy earlier in retirement.
You might want to take a special trip, pursue a meaningful hobby, or spend time with people you love while you’re still healthy enough to participate fully.
That doesn’t mean ignoring the financial consequences of your decisions. It also means considering the consequences of waiting.
For more on this topic, see Bucket List Planning: Align Your Health With Your Goals.
Understanding the Retirement Spending Smile
Many retirement projections assume spending remains relatively consistent, increasing each year with inflation.
But actual retirement spending often follows a different pattern.
The retirement spending smile describes a pattern in which inflation-adjusted spending starts higher, declines during the middle years, and may rise later as healthcare and other care-related costs increase. However, not everyone follows this pattern, and retirement spending often continues to decline in later years.
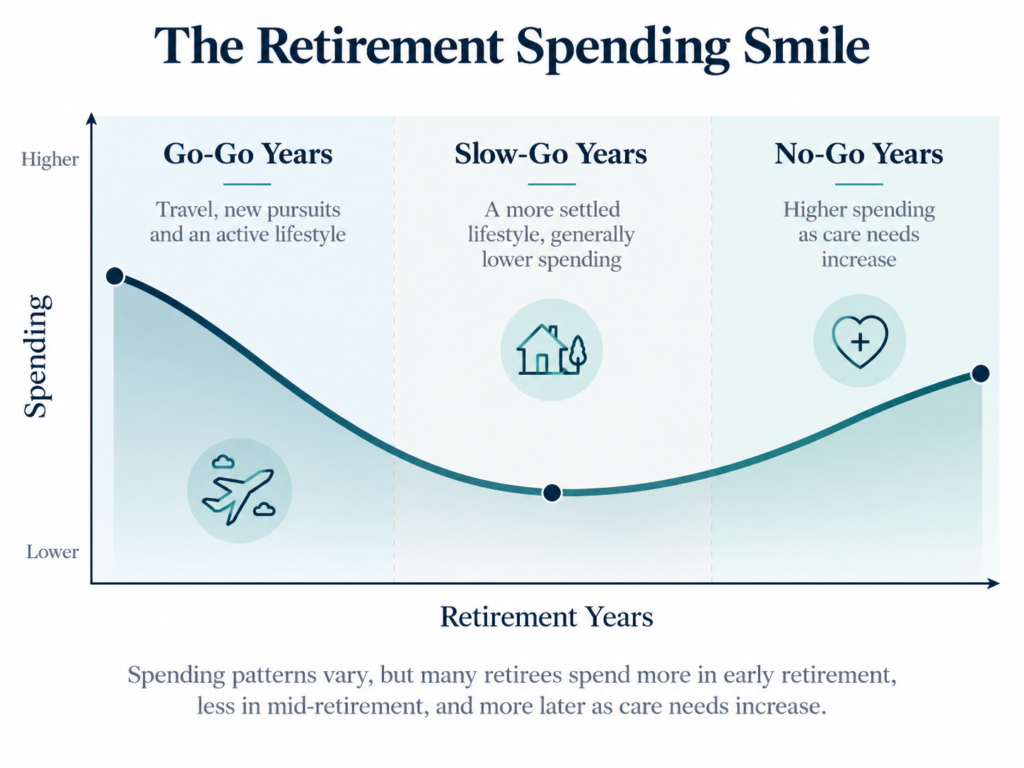
In updated research published in 2026, David Blanchett found that retirement spending can follow either a smile or a more gradual decline. Average spending patterns can differ from those of the typical retiree, in part because some retirees face substantial healthcare expenses later in life. The important point is that spending needs change, and retirement plans should reflect that.
You may also have heard retirement described in terms of three stages:
The go-go years: Early retirement, when you’re generally more active and may spend more on travel, activities, and experiences.
The slow-go years: Middle retirement, when activity levels and certain discretionary expenses may decline.
The no-go years: Later retirement, when activities may become more limited and healthcare or support needs may increase.
These aren’t rigid categories, and not everyone’s spending will follow this pattern. But they help illustrate an important point.
You don’t necessarily need to spend the same amount every year in retirement. A thoughtful financial plan can let you spend more in your active years while still preparing you for potential healthcare and long-term care costs later.
Learn more in my blog, The Retirement Smile: Navigating the Phases of Financial Freedom.
Remember Why You Saved
Most of us didn’t save for retirement just to build the largest possible account balance. We saved to support ourselves and enjoy a meaningful life after we stopped working.
Some people have important goals involving children, other family members, or charitable organizations. Don’t ignore those priorities. But unless leaving an inheritance is your primary goal, you shouldn’t automatically place preserving every possible dollar ahead of enjoying your retirement.
A thoughtful financial plan can help you balance enjoying retirement today with protecting your financial security tomorrow.
8. Plan for Housing, Healthcare, and Future Support
Where you live and the support you may need as you age are important retirement planning considerations.
Some women prefer to remain in their current home. Others may want to downsize, relocate, move into a 55-plus community, or consider a continuing care retirement community.
Where you live influences your daily activities, relationships, access to healthcare, transportation, and opportunities to remain engaged in your community.
The question isn’t simply whether you can afford your home. It’s also whether that home supports the life you want today and is likely to meet your needs as you get older.
Healthcare coverage also deserves attention, especially if you’re considering retiring before age 65. You’ll need to evaluate how to maintain coverage until you’re eligible for Medicare, what that coverage may cost, and how healthcare expenses fit into your overall retirement plan.
What Happens if You Need Long-Term Care?
This is a difficult question, but it matters.
Would you prefer to age in place and receive care at home, or would assisted living or a continuing care retirement community better meet your needs? What support might family members or others be able to provide?
While couples sometimes have a spouse available to help with care needs, that isn’t always the case. Similarly, being single doesn’t mean you lack family, friends, or other people who can help.
What matters is understanding what support may be available and planning for the possibility that you may need additional assistance.
How Will You Pay for Long-Term Care?
Long-term care insurance is one option worth evaluating. However, premiums can be expensive, and many people decide insurance isn’t the right solution.
Other approaches include setting aside resources or incorporating potential care expenses into your financial plan.
At Apprise, we ask clients whether they would prefer to receive care at home, in an assisted living community, or in a nursing facility. We then use the Genworth/CareScout Cost of Care Survey to estimate potential expenses based on their preferred type of care and where they expect to live in retirement.
We typically model at least three years of potential long-term care expenses. Of course, these are planning assumptions, not guarantees. Actual care needs, costs, and available options may differ from what someone originally envisioned.
We can also examine how needing more than three years of long-term care could affect the plan.
The Administration for Community Living estimates that women need long-term care services and support for an average of 3.7 years. Approximately 20% of people turning 65 will need care for more than five years. These figures include different forms of assistance, including unpaid care, and don’t necessarily reflect how many years someone will need paid in-home or residential care.
Don’t Forget Your Estate Planning Documents
Also consider who can manage your affairs if you can’t.
Important documents may include a will, financial power of attorney, healthcare directive, and other documents your estate planning attorney recommends.
You should also review beneficiary designations and identify trusted contacts for your financial accounts.
A trusted contact gives your financial institution someone to contact if concerns arise, but doesn’t authorize that person to make decisions or transactions on your behalf. The SEC explains this distinction in its investor bulletin on trusted contacts.
At Apprise, we cover these issues as part of comprehensive financial planning, but an estate planning attorney generally handles preparing and reviewing legal documents.
The goal is to help you identify what needs attention and ensure the right professionals are involved.
9. Review Your Retirement Plan and Be Willing to Adjust
Retirement planning isn’t something you complete once and never revisit. Your priorities, investments, health, family circumstances, and spending needs will change over time. Regular reviews can help you identify tax-planning opportunities, adjust your investments and withdrawals, and determine whether your financial strategy still supports your goals.
As you review your plan, consider three questions: Can my resources support my essential expenses? What spending could I adjust if circumstances change? Am I making room for the experiences and priorities that matter most to me?
The answers can help you decide whether your plan needs attention, even if your circumstances haven’t changed much.
Sometimes, a review may even reveal that you can comfortably spend more than you previously thought.
Retirement Planning for Single Women: Frequently Asked Questions
1. How much money does a single woman need to retire?
There’s no universal amount. It depends on your desired lifestyle, retirement age, Social Security benefits, investments, taxes, healthcare needs, and longevity. Start by identifying the life you want to live, then determine the resources needed to support it.
2. Is retirement planning harder for single women?
Not necessarily, but it involves different considerations. Social Security, taxes, retirement income, housing, and future care needs may require different strategies. Being single doesn’t automatically mean being less financially secure. What matters is having a plan that reflects your circumstances.
3. Should a single woman wait until age 70 to claim Social Security?
Not necessarily. Waiting until age 70 maximizes your monthly retirement benefit based on your own earnings record. However, the right claiming age depends on your health, anticipated longevity, financial resources, and eligibility for other Social Security benefits.
4. Should single women invest more conservatively as they approach retirement?
Not automatically. An overly conservative portfolio can increase inflation and longevity risks. Your investments should balance near-term withdrawal needs with long-term growth, while reflecting your risk tolerance and financial goals.
5. Why is tax planning important for single women in retirement?
Single taxpayers generally face narrower tax brackets than married couples filing jointly. Coordinating Roth conversions, retirement withdrawals, and investments can help manage your lifetime tax burden and preserve more of your retirement resources.
6. What if I don’t know what I want my retirement to look like?
That’s a good reason to start with life planning. Exploring your values, priorities, and aspirations can help you identify what matters most and build a financial plan that supports the retirement you want.
Ready to Explore Your Retirement Plans?
Are you wondering whether you’re financially prepared for retirement and what you want your retirement to look like?
Retirement planning for single women involves more than financial security. It’s about understanding what matters most to you and using your resources to support the life you want to live.
At Apprise, we believe life planning and financial planning belong together. You can’t eliminate every uncertainty about retirement, but you can prepare for the unexpected, make informed decisions, and leave room to enjoy the life you’ve worked to build.
Are you wondering whether you’re financially prepared for retirement and what you want your retirement to look like?
If you’d like to explore how financial and life planning can help you prepare for a meaningful retirement, I invite you to schedule a discovery call with Apprise Wealth Management. We can discuss your goals and concerns and whether our approach is a good fit.
Related Reading
- When to Claim Social Security: How to Think About 62, FRA, and 70
- How Is Retirement Income Taxed?
- Bucket List Planning: Align Your Health With Your Goals
- The Retirement Smile: Navigating the Phases of Financial Freedom
- Asset Location for Tax Efficiency
For firm disclosures, see Apprise Wealth Management disclosures.
Our practice continues to benefit from referrals from our clients and friends. Thank you for your trust and confidence.
Follow us: Facebook | LinkedIn | Instagram | YouTube
Please note. We post information about articles we think can help you make better money-related decisions on LinkedIn, Facebook, Instagram, and YouTube.
Phil Weiss founded Apprise Wealth Management to help women facing new beginnings understand their financial lives, make thoughtful decisions, and use their money in ways that support what matters most to them.